Crypto futures trading has become the fastest-growing segment of India’s digital asset market, and the reason is simple: it lets you profit when prices fall, use leverage to control a larger position than your capital would otherwise allow, and hedge existing holdings, all without ever taking custody of the underlying coin.
It is also the segment where Indian traders most frequently get the tax treatment wrong.
India’s crypto tax framework was drafted in 2022 with spot buying and selling in mind. Crypto futures trading sits awkwardly between that framework and the older rules governing derivatives, and the government has not issued a definitive clarification. This guide explains the mechanics, the costs, the legal position, and most importantly exactly where the tax law is settled and where it is not.
What is crypto futures trading?
Crypto futures trading means buying or selling a contract whose value tracks the price of a cryptocurrency, rather than buying the cryptocurrency itself.
When you buy Bitcoin on a spot market, you own Bitcoin. When you open a long position in a Bitcoin futures contract, you own an agreement that gains value if Bitcoin rises and loses value if it falls. No Bitcoin changes hands.
That distinction unlocks three capabilities that spot trading cannot offer:
- You can go short: If you believe Ethereum will fall, you can sell a futures contract and profit from the decline. On a spot market, your only options are to sell what you hold or stay out.
- You can use leverage: Futures are margin products. A ₹10,000 margin deposit at 10x leverage controls a ₹100,000 position. Gains and losses are calculated on the full position size, not on your margin.
- You can hedge: A long-term holder worried about a short-term correction can open a short futures position to offset losses on their spot holdings without selling them, which matters in India, where selling triggers a taxable event.
Perpetual contracts versus dated futures
Most crypto futures trading in India happens through perpetual contracts, which have no expiry date. You can hold a position indefinitely, provided you maintain sufficient margin.
Because perpetuals never expire, they need a mechanism to keep the contract price anchored to the spot price. That mechanism is the funding rate, a small periodic payment (usually every eight hours) exchanged directly between long and short traders. When the contract trades above the spot, longs pay shorts. When it trades below, shorts pay longs.
Dated futures expire on a set date and settle at a reference price. They are less common in Indian retail crypto futures trading but are used by traders who want defined-duration exposure without funding costs.
The mechanics you must understand before you start
Margin
Initial margin is the capital required to open a position. Maintenance margin is the minimum that must remain in the position to keep it open.
Most Indian platforms offer two modes:
- Isolated margin: the margin is confined to a single position. If it liquidates, your loss is capped at that margin. Recommended for beginners.
- Cross margin: your entire account balance backs every open position. This reduces liquidation risk on any single trade but exposes your whole balance if things go badly.
Leverage and liquidation
This is where most new entrants to crypto futures trading lose money, so it deserves plain arithmetic.
At 10x leverage, a 10% adverse move wipes out your margin entirely. At 50x leverage, a 2% adverse move does it. At 100x leverage, roughly 1% is enough.
Bitcoin routinely moves 2–3% in a single session. A 100x position in a normal market is not a trade; it is a countdown.
Liquidation is the forced closure of your position when margin falls below the maintenance requirement. The exchange closes it automatically to prevent your account going negative. Most platforms charge a liquidation fee on top of the loss.
High leverage is a professional tool used with tight, pre-planned risk limits. It is not a way to compensate for a small account.
Mark price
Liquidations are triggered by the mark price, a smoothed index derived from multiple sources rather than the last traded price on a single venue. This exists to prevent a brief wick on one exchange from liquidating positions unfairly. Knowing which price governs your liquidation is essential.
INR-Margined vs. USDT-Margined Contracts
This is the single most important structural decision in Indian crypto futures trading, and it affects both your costs and your tax position.
USDT-margined contracts require you to convert INR into USDT first, then trade. Every conversion in and out is a separate transaction with its own cost and, critically, its own tax consequence.
INR-margined contracts let you post rupees directly as margin. There is no stablecoin conversion leg on entry or exit.
The practical difference over a year of active trading is substantial. Each INR→USDT→trade→USDT→INR round trip carries conversion spread and potential TDS on the crypto-to-crypto legs and additional entries to reconcile at filing time. INR-margined crypto futures trading removes those legs entirely.
The tax difference is covered below, and it is more significant than the cost difference.
Is crypto futures trading legal in India?
Yes, with an important qualification.
Crypto is legal to trade in India but remains unregulated. It is not legal tender, and there is no SEBI-equivalent regulator supervising crypto derivatives the way SEBI supervises equity F&O.
What the law does require is that any platform serving Indian users registers with the Financial Intelligence Unit of India (FIU-IND) under the Prevention of Money Laundering Act. Registered entities must run KYC, maintain records, and report high-value and suspicious transactions to the government.
This is not a formality. In January 2025, the government blocked several offshore exchanges operating without FIU registration, disabling deposits and trading for Indian users. Some platforms took months to restore full service.
Practical guidance: trade crypto futures only on FIU-registered platforms. Verify registration before depositing. An unregistered offshore platform can lose Indian market access with no notice, and you will have no domestic grievance redressal if something goes wrong.
The Tax Treatment
Most articles on crypto futures trading in India state a single confident answer here. That is misleading. The law is genuinely unsettled, and any honest guide has to say so.
The starting point: Section 115BBH
The Finance Act 2022 introduced Section 115BBH, imposing a flat 30% tax (plus 4% cess and any applicable surcharge) on income from the transfer of a virtual digital asset, as defined under Section 2(47A).
Three features make this among the harshest crypto tax regimes in the world:
- Only the cost of acquisition is deductible. No trading expenses, no platform fees, no infrastructure costs.
- No loss set-off. VDA losses cannot offset salary, business income, or capital gains, and under the prevailing interpretation, not even gains on other VDAs.
- No carry-forward. A loss expires on 31 March. There is no memory in the system.
Where crypto futures trading creates genuine ambiguity?
Traditional derivatives in India are taxed as business income at slab rates, with expenses deductible and losses eligible for set-off and carry-forward. Equity F&O on the NSE works this way.
Crypto futures sit between the two regimes, and the question turns on a single statutory word: transfer.
For USDT-settled perpetuals, the position is relatively clear. Profit and loss are realized in USDT, which is itself a VDA. Tax professionals widely treat these as VDA transactions, 30% under Section 115BBH, 1% TDS on settlement value, and no loss set-off.
For INR-settled contracts, a technically defensible alternative exists. Where a contract is margined and settled entirely in rupees with no actual delivery of cryptocurrency, there is a sustainable argument that no VDA “transfer” occurs and that the income should be taxed as speculative or non-speculative business income at slab rates under normal provisions.
But this is not confirmed by the CBDT. There is no circular resolving it and no definitive judicial guidance. The tax authorities have taken a consistently aggressive stance on VDA matters, and many chartered accountants therefore apply the conservative 30% treatment to INR-settled crypto futures as well.
What this means for you: if you trade crypto futures in India, this is a question to resolve with a qualified CA who has reviewed your actual contract notes, P&L statements, and the platform’s terms, not a question to settle by reading a blog. The difference between 30% flat and slab-rate business income treatment can be very large, and so can the penalty for getting it wrong.
The 1% TDS under Section 194S
Section 194S requires 1% TDS on the transfer of a VDA, deducted by the exchange at the time of payment.
Thresholds are based on cumulative VDA transaction value in a financial year:
- ₹50,000 for specified persons (broadly, individuals and HUFs without business turnover above prescribed limits)
- ₹10,000 for other taxpayers
TDS is not an additional tax. It is advanced tax credited against your final liability and visible in Form 26AS and your AIS. If your actual liability is lower, you claim a refund.
FIU-registered Indian exchanges typically deduct and remit this automatically. On offshore platforms, compliance responsibility is far murkier and frequently falls on the trader.
GST on fees
18% GST applies to exchange trading and service fees. This is levied on the fee, not on your trade value or your profit. A quoted taker fee of 0.0580% is effectively 0.0684% after GST.
Reporting: Schedule VDA and ITR forms
All income from crypto futures trading, options, perpetuals, spot, and NFTs must be disclosed in Schedule VDA of your income tax return.
- ITR-2 — for occasional spot activity without business intent
- ITR-3 — the safer choice if your crypto futures trading is at all frequent, or if you are taking a business-income position
The filing deadline for FY 2025–26 is 31 July 2026 for non-audit cases. Verify current dates, as extensions are common.
Enforcement has tightened sharply in 2026.
This is the practical change traders most underestimate.
Exchange data sharing with the Income Tax Department is now live. TDS entries appear automatically in your AIS. FIU-registered platforms report under PMLA obligations. The department can and does match declared income against exchange-reported activity.
Penalties for under-reporting range from 50% to 200% of the tax owed, plus interest, and in serious cases, prosecution exposure.
The era in which crypto activity was practically invisible to the tax department has ended.
A worked example
You deposit ₹1,00,000 and trade crypto futures actively for a year. You close FY 2025–26 with ₹40,000 in gross profits and ₹15,000 in realized losses.
Under the conservative VDA treatment:
- Taxable income: ₹40,000 The ₹15,000 loss cannot be offset
- Tax at 30%: ₹12,000
- Cess at 4%: ₹480
- Total: ₹12,480
- Platform fees paid during the year: not deductible
- TDS already deducted: credited against this liability
Your net profit before tax was ₹25,000. Your tax bill is ₹12,480; an effective rate near 50% of actual economic profit.
That asymmetry is the defining feature of crypto futures trading in India, and it should shape your position sizing before it shapes your filing.
How to start crypto futures trading in India?
Step 1 — Start with an FIU-registered, Indian crypto trading platform
Before anything else, confirm the platform is registered with FIU-IND. Offshore exchanges operating without registration have been blocked in India before, leaving users unable to trade or deposit for months.
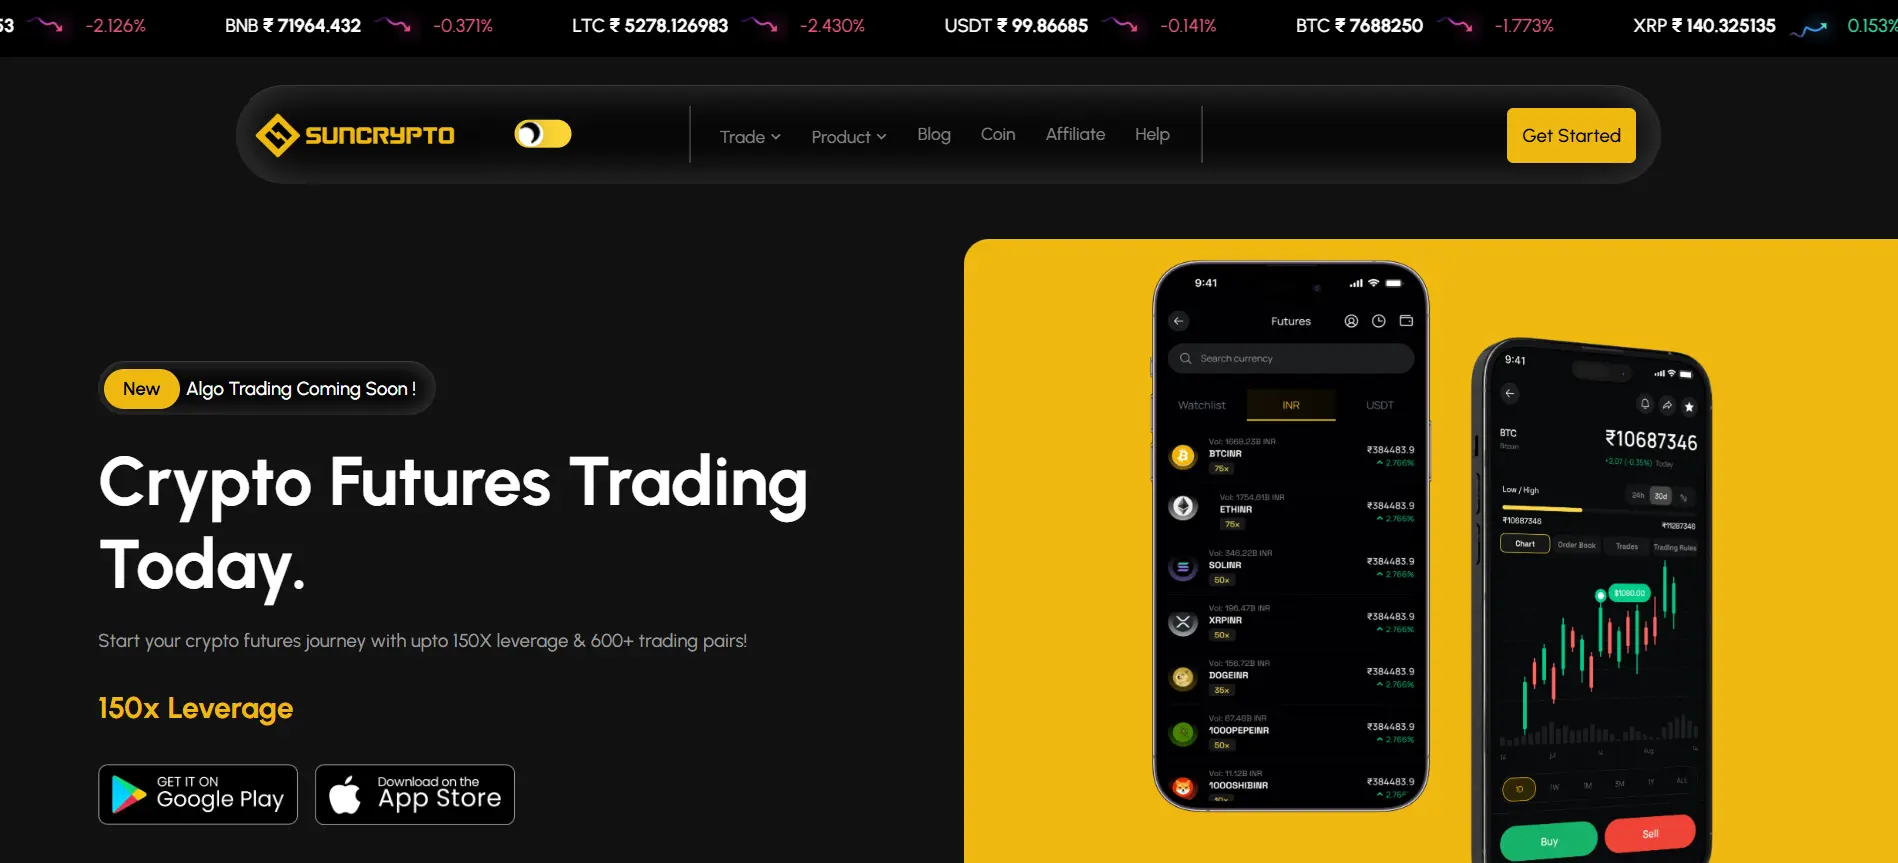
SunCrypto is an India-domiciled, FIU-registered exchange governed by Indian law, and it meets the checklist that matters for crypto futures trading:
- INR-margined futures: post rupees directly as margin, with no USDT conversion leg on entry or exit
- Tiered futures trading fees: VIP 0 at 0.0300% maker / 0.0580% taker, scaling to 0.0075% / 0.0300% at VIP 7
- Deposit rails: UPI, IMPS, NEFT, and RTGS
- A compliant INR exit: dedicated USDT-to-INR conversion with 1% TDS deducted and remitted automatically
- 600+ trading pairs across INR and USDT markets
- Risk tooling: stop-loss, take-profit, professional charting, plus bot and algo trading
- Zero account-opening and maintenance charges
Step 2 — Complete KYC
PAN, Aadhaar, and a bank account in your own name. Third-party deposits are rejected and create compliance problems that are tedious to unwind.
Step 3 — Deposit in INR
Fund the Suncrypto wallet account via UPI, IMPS, NEFT, or RTGS. Start with the capital you can afford to lose entirely. Crypto futures trading is a leveraged product, and a total loss of margin is a normal outcome, not an edge case.
Step 4 — Learn the interface on minimum size
Place small trades first. Understand order types (market, limit, stop), how margin is displayed, exactly where your liquidation price sits, and how funding is charged on perpetual contracts. The cost of learning this for ₹500 is trivial. The cost of learning it on ₹50,000 is not.
Step 5 — Set leverage deliberately
Begin at 2x to 5x. At 1x, a futures position behaves like a spot with the added ability to go short. SunCrypto supports higher leverage on eligible contracts, but availability is not a recommendation at 50x; a 2% adverse move liquidates the position, and Bitcoin moves that much routinely. The traders who last rarely use the maximum on offer.
Step 6 — Define risk before entry
Set your stop-loss and take-profit when you open the trade, not after it moves against you. A standard discipline: risk no more than 1–2% of account capital per trade. SunCrypto’s Expert Picks can help newer traders read futures-market setups, but no insight removes the need for your own stop.
Step 7 — Keep records from day one.
Download your contract notes, P&L statements, and TDS certificates monthly from the app rather than reconstructing a full year in July. Because INR-margined trades skip the USDT conversion legs, your transaction trail is materially shorter and easier to reconcile at filing time.
Step 8 — Engage a CA early
Given the unsettled question of whether crypto futures income falls under the 30% VDA regime or business-income treatment, get professional advice before the financial year closes, not after, when your position is already fixed.
The full cost of a crypto futures trading
Headline fee comparisons mislead because they omit most of the cost stack. The real components:
| Cost | What it is |
| Maker fee | Charged when you add liquidity (limit order) |
| Taker fee | Charged when you remove liquidity (market order) |
| GST | 18% on the fee |
| Funding rate | Periodic payment between longs and shorts on perpetuals |
| Slippage | Difference between expected and executed price |
| Conversion spread | On USDT-margined trades, both directions |
| TDS | 1% where applicable |
| Liquidation fee | If the position is force-closed |
For a high-frequency trader, funding costs and slippage routinely exceed nominal trading fees. Compare the total round trip, not the advertised rate.
Common mistakes in crypto futures trading
- Using maximum leverage because it is available. Availability is not a recommendation.
- Not knowing the liquidation price. It should be the first number you check after opening a position.
- Ignoring funding rates. In a strongly trending market, funding can quietly consume a substantial portion of a profitable position held over weeks.
- Adding margin to a losing position. Defending a bad trade converts a small loss into a large one.
- Assuming losses reduce your tax bill. Under the VDA regime they generally do not. This is counterintuitive for anyone coming from equity F&O.
- Trading on unregistered offshore platforms. Cheaper fees do not compensate for the loss of domestic recourse and unclear TDS compliance.
- Treating crypto futures trading as an income substitute. It is a high-variance activity. Most retail participants in leveraged derivatives lose money over time, in every market and every jurisdiction.
The bottom line
Crypto futures trading offers Indian traders genuine capabilities that spot markets cannot: shorting, leverage, and hedging without triggering a disposal. Those capabilities are real and, used with discipline, useful.
But the Indian tax structure changes the math in a way most traders discover too late. Losses do not reduce your bill. Fees are not deductible. A trader who is modestly profitable on paper can be barely breakeven after tax.
And the classification question of 30% VDA treatment versus business income remains unresolved in law. Anyone engaged in serious crypto futures trading in India should resolve that question with a qualified professional, using their own contract notes, before the financial year closes.
Is crypto futures trading legal in India?
Yes, but crypto remains unregulated and is not legal tender. Trade only on FIU-IND registered platforms, and report all income in Schedule VDA of your ITR.
How is crypto futures trading taxed in India?
Conservatively, at a flat 30% plus 4% cess under Section 115BBH, with 1% TDS under Section 194S, no deductions except cost of acquisition, and no loss set-off or carry-forward. For INR-settled contracts, a business-income treatment at slab rates is technically defensible but not confirmed by the CBDT. Consult a qualified CA.
Can I set off crypto futures losses against my salary or stock gains?
No. Under Section 115BBH, VDA losses cannot be set off against any other income, and under the prevailing interpretation, not even against gains on other VDAs. They also cannot be carried forward.
Is the 1% TDS an extra tax?
No. It is advance tax, credited against your final liability and visible in Form 26AS and your AIS. Excess TDS is refundable.
What leverage should a beginner use?
2x to 5x. At 50x, a 2% adverse move liquidates the position. Bitcoin moves that much routinely.
What is the difference between INR-margined and USDT-margined crypto futures?
INR-margined contracts let you post rupees directly as margin. USDT-margined contracts require conversion into USDT first, adding cost, an extra transaction leg, and additional tax complexity. USDT-settled profits are clearly VDA transactions; INR-settled ones are the contested category.
What is the funding rate?
A periodic payment exchanged between long and short traders on perpetual contracts, keeping the contract price anchored to spot. It is a real cost that compounds on positions held over time.
Which ITR form do I use?
ITR-2 for occasional spot activity; ITR-3 if your trading is frequent or you are taking a business-income position. All VDA income goes in Schedule VDA.
Can the Income Tax Department see my crypto trades?
Yes. Exchange data sharing is live, TDS appears automatically in your AIS, and FIU-registered platforms report under PMLA. Under-reporting penalties range from 50% to 200% of tax owed.
Do I pay GST on crypto futures trading?
18% GST applies to exchange fees, not to your trade value or profits.
Can I lose more than I deposit?
On most retail platforms, no positions are liquidated before the account goes negative. But you can lose your entire margin very quickly, and liquidation fees apply on top.